

I’m proud to announce that this post has been featured on The Tao of Stock Trading from the DailyMoat.com - Jack is an ex-hedge fund manager and his investing letter has nearly 700,000 readers! Go check them out!
Hello! For those of you who joined recently, let us introduce ourselves. We are MktContext.com and we’ve been beating the market since 2014.
I am a professional money manager, trader, and investor. I’ve managed $5B AUM at a major bank. I focus on timing the market - YES, it’s possible! This weekly letter will give you the analysis and tools to do the same. Subscribe below for free and join us!
✅Here’s our past note where we called the market top by using a SINGLE indicator.
✅And we predicted the pattern of this week’s selloff before it happened.
Our approach - Why do we trade our portfolio?
We often get asked why we trade in and out of our entire portfolio (sometimes getting whipsawed!) instead of just holding for the long run. There is well-documented evidence that market timing can outperform a simple buy-and-hold strategy. This is how we’ve managed to beat the market for nearly a decade.
By swinging our portfolio at opportune times, sometimes going into 100% cash, we can stay 100% invested in equities most of the time. This allows us to capture the high returns that this asset class has historically offered, without the significant drawdowns that it periodically suffers.
The typical stock/bond portfolio’s returns are significantly dragged down by the bond portion. Historically, bonds were needed to protect on the downside. But if we can find other ways to protect us, then we can remove this drag and amplify our long-term returns. Important: In an inflationary regime like we are in now, bonds do NOT protect on the downside. Therefore, the typical 60/40 stock-and-bond portfolio will not protect investors the same way they have for the past four decades. Holding bonds in today’s world is a recipe for mediocrity.
By being proactive in our trading, we’ve been able to avoid major drawdowns like in 2020 and 2022, reducing portfolio volatility. We enjoy all the upside of owning 100% stocks while limiting some of the risks. Of course, our approach isn’t without risks. There will be times when we get whipsawed and our trades don’t work out as planned. There will be times we sell the portfolio, only to re-enter at a higher price. It sucks, but that’s all part of the process!
Market update
Last week we witnessed a 5% selloff in SPX. It first started with the soft inflation data two weeks ago, which triggered a momentum squeeze out of tech stocks and into small cap stocks. The selloff was then accelerated by problems at chip companies, weak earnings results from GOOG and TSLA, and the CrowdStrike fiasco.
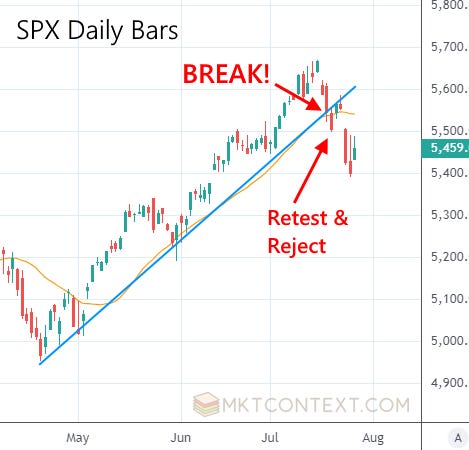
This is the crucial break we saw at the time: a break of the clean uptrend since the April lows. The break was further confirmed by a retest-and-reject (as we predicted) at which point we sold 30% of our portfolio to cash. Always trade in tranches to avoid whipsaw.
The market continued to sell off but showed signs of life by the end of the week. The SPX bounced at the 50d moving average, while the QQQ bounced at the 100d (this is a tech-led selloff so we need to watch Nasdaq as well). Furthermore, the QQQ rejection occurred at the -10% price level (psychological level), the 50% retracement level, and the anchored VWAP from April lows. Nasdaq-100 put/call ratios are also showing extreme negative sentiment. Sometimes, Nasdaq tells a better story than the S&P500!
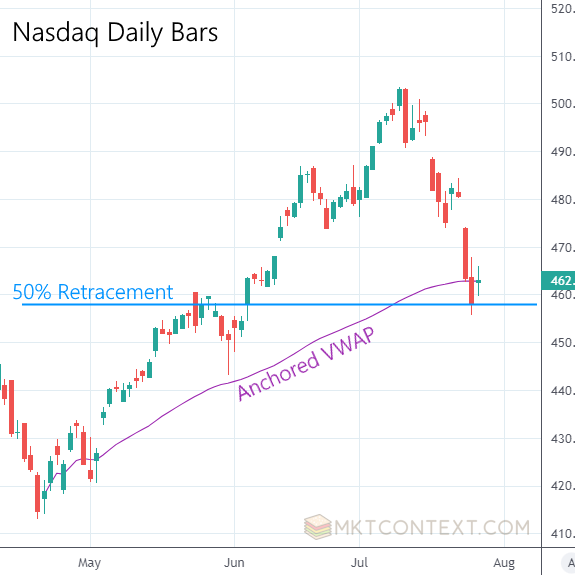
Note: If you don’t know what any of these indicators are, no worries as we will explain them in future posts. Suffice it to say this is a logical pivot point and we await further clues on what’s to come next.
Positioning unwind is done
Understanding the reason for a drop can help determine how soon/quickly a rebound will take place. For example, a simple unwind of a crowded trade should be shorter-lived and shallower than a structural deterioration in earnings or the macroeconomy.
As mentioned earlier, there was the large-to-small-cap unwind that was already underway. But this week there were simultaneously two other cross-asset-class unwinds that added fuel to the fire. (Shoutout to Brent Donnelly over at Spectra Markets for this insight. Brent is a trading veteran who writes an incredible daily newsletter - go check him out!)
The first is the carry trade in USDJPY. The carry trade worked by capturing the huge interest rate difference between the US Dollar and Japanese Yen. With the two rates set to converge again, traders were forced to unwind the trade, causing a sharp selloff in the USDJPY exchange rate. This has transmission mechanisms to equity markets, particularly Nasdaq.
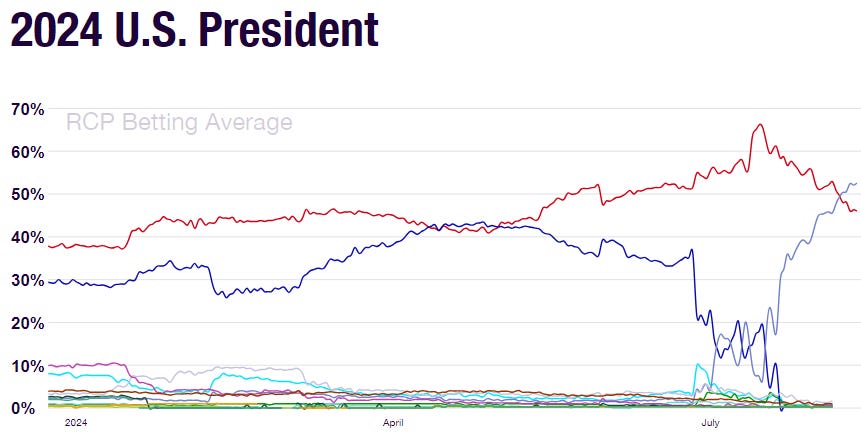
The second event was Biden announcing his exit from the presidential race. As Trump’s odds of winning soared to extreme levels, traders bought the SPX assuming his tax cuts and fiscal policies would be bullish - the same playbook from 2016. But Trump’s winning odds were already at unsustainable extremes (67% on betting sites). With the entrance of a viable candidate like Kamala Harris, markets realized this would not be a landslide win for Trump and had to unwind that trade as well. This had a profound impact on large cap tech stocks:
In sum, three separate “squeezes” that forced traders to sharply sell SPX and QQQ. Understanding other traders’ positioning is like knowing your opponent’s hand in poker. The above shifts are short-term in nature and do not jeopardize the longer-term picture of strong earnings in a resilient economy. We want to be dip buyers when markets are panicking momentarily.
Predicting the next two weeks
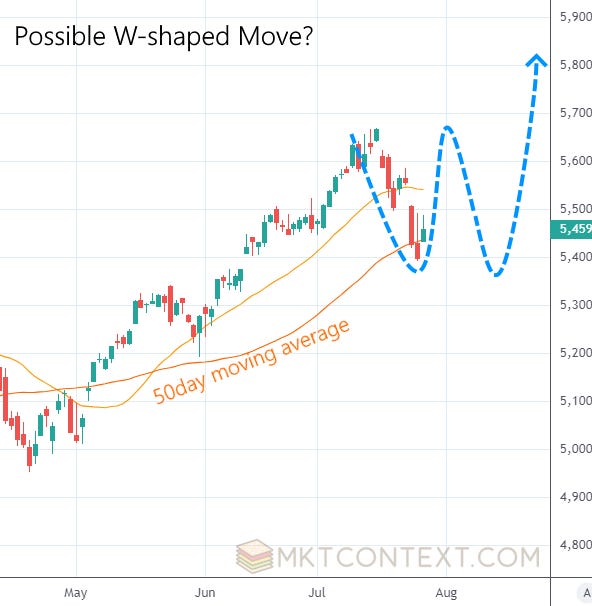
We are currently waiting for either a continuation to the downside, or V-shaped recovery to the highs. Key upcoming catalysts that could move the market in either direction include: earnings from mega cap tech companies, economic data for jobs and manufacturing, and an FOMC meeting at the end of the month.
Looking at these catalysts, we think the market is likely to bounce from here for these reasons (we’ll elaborate later in this letter):
Corporate earnings are strong, not just for tech but for the broader index of companies.
The economy continues to be resilient with consumers spending and manufacturers recovering.
Inflation continues to fall which should allow the Fed to cut interest rates sooner rather than later.
Next, we use technical analysis to confirm our macroeconomic thesis. The bounce is confirmed if QQQ breaks its downtrend structure and put/call ratios normalize. The put/call ratio picks up timing signals from the options market, and is an indicator of “frenzy” in the market… we need it to calm down. Lastly, we would also prefer to see breadth thrusts on the upside, meaning the entire market is participating in the rally.
If a V-shaped rally occurs, readers will recall that we have a stop-buy on SPX at $5,650. That means if SPX rebounds to highs, we must re-enter into the market at 100%. This is necessary to prevent us from missing the upside if we’re wrong. What people don’t tell you about market timing is that you must time the entry AND the exit; one or the other won’t suffice. I have seen too many investors sell out just to get “locked out” of the next rally.
On the other hand, a definitive break of the 50d moving average in SPX (100d in the QQQ) would confirm further downside. This is not impossible as the broader market is not showing extreme pessimism as it usually does at the bottom of a selloff. A further selloff would be unlikely given small caps are buttressing the market, but if it were to happen, we would sell another 30% of our portfolio.
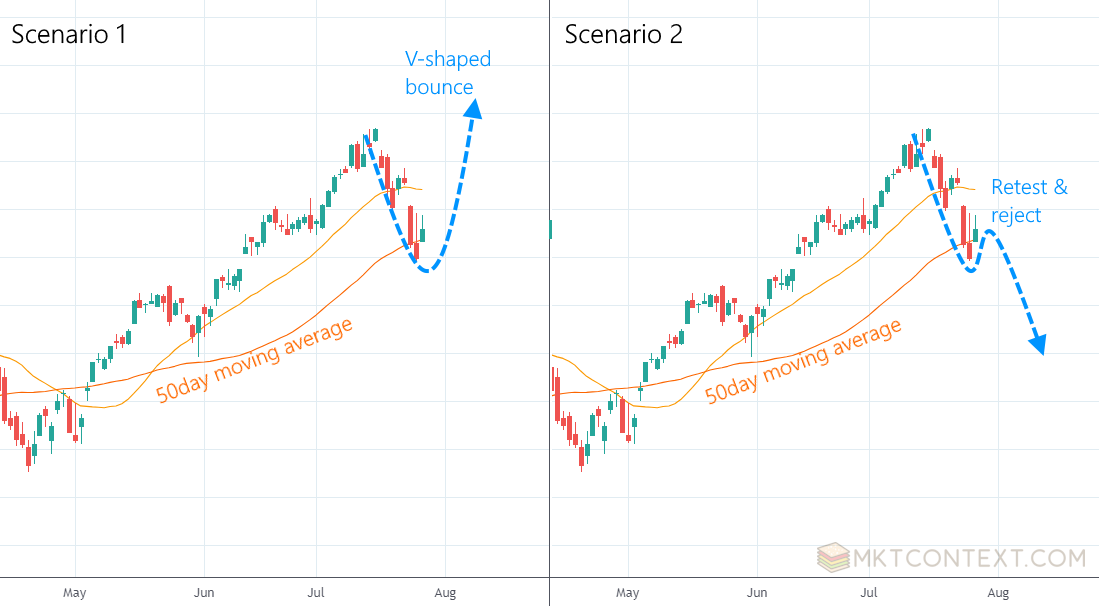
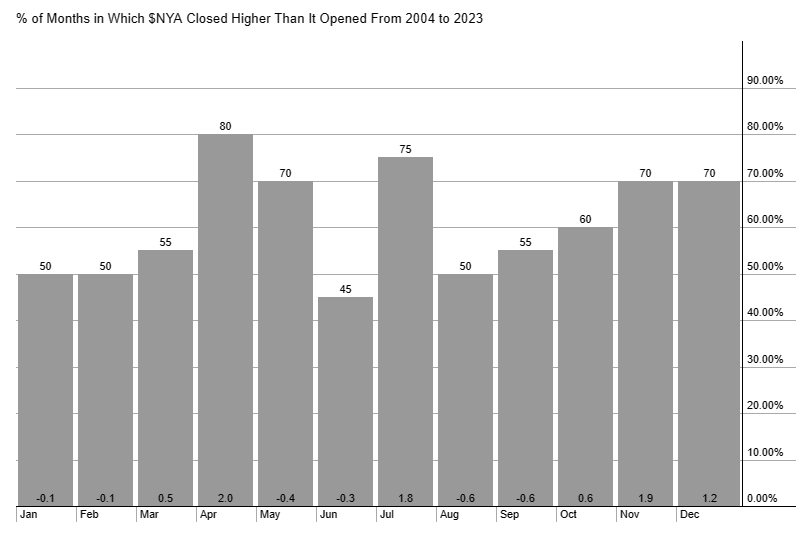
To further complicate things, August and September tend to be seasonally weak months. Also, we have an election coming up and markets tend to throw a tantrum roughly 2 months prior to voting day. This means we could see a W-shaped move like so:
If you’re wondering the reasoning behind Aug and Sept weakness, there are a few theories out there. But it’s generally understood that fund managers are away on vacation, leaving poor market liquidity, around the same time people liquidate stocks to pay for school tuition. Regardless of the reason, seasonality is just a rough guide and can’t be relied upon heavily. Note that the last few years have respected the seasonal pattern:
The thesis for small caps
I’ve been hearing a lot of skepticism out there that small caps can continue their monstrous rally. It’s true, the IWM (Russell 2000 ETF) was rangebound the past two weeks. Naysayers suggest the US economy is heading for a recession while inflation continues to run hot, both of which should be bad for small caps. This view is misguided.
By all accounts, the economy is NOT headed for a recession. Bears will cherry-pick bad data points, but ignore the reality that this economic cycle has been very different from past ones because of Covid distortions. Economists’ models aren’t tuned to pick up on the nuance - we wrote a post about this before but let’s recap a few points:
Homeowners and corporates immunized themselves from rising interest rates and are actually benefiting from Fed tightening. People are spending money because they remain gainfully employed as wages are rising. Sure, there is some pain in lower-income consumers, but the middle and upper brackets are feeling WEALTHIER and are out there spending on vacations and experiences. To top it off, the current reported GDP grew nearly 3%. That simply doesn’t happen in recessions.
Meanwhile, inflation continues to fall, a fact that many refuse to believe. What’s caused inflation angst is stubborn car insurance and shelter prices, which are both notoriously laggy. But they are trending in the right direction. This week’s core PCE came in at 2.2% annualized; does anyone look at the below chart and think inflation is rising?!
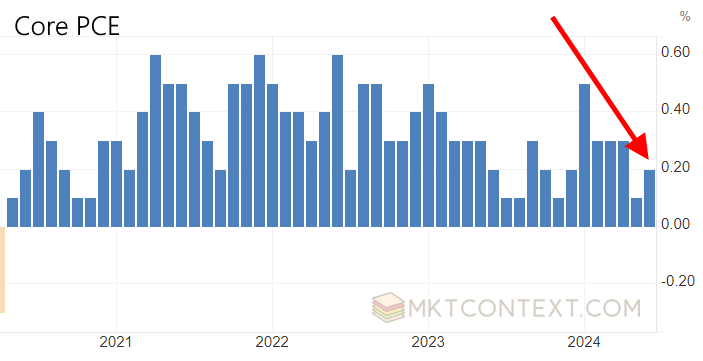
With inflation down near the Fed’s magical 2% target, they have a reason to start cutting soon. Economic growth + falling inflation is a potent mix to fuel small cap stocks. More importantly, the market historically doesn’t price-in the full move until the actual cut, meaning there is more room to rally.
What about earnings? Earnings for the S&P 493 (i.e. S&P 500 ex. Mag 7) are coming out of a two-year slowdown and inflecting upwards. Estimates are being revised higher, and ALL sectors are participating in the improvement. This is key as it gives fundamental investors a reason to start allocating funds to small caps. In this segment of the market, it looks like we’re coming OUT of a recession, not heading INTO one.

Technical analysis of IWM
Technicals are not just about drawing lines on a chart (it is, but it’s also a lot more). It includes analyzing the components of the index and the positioning of other traders. Sort of like playing poker and analyzing the deck and other players at the table. On that note, IWM has a great technical setup right now. A break of the two-week range would be a clear signal for a rally continuation:
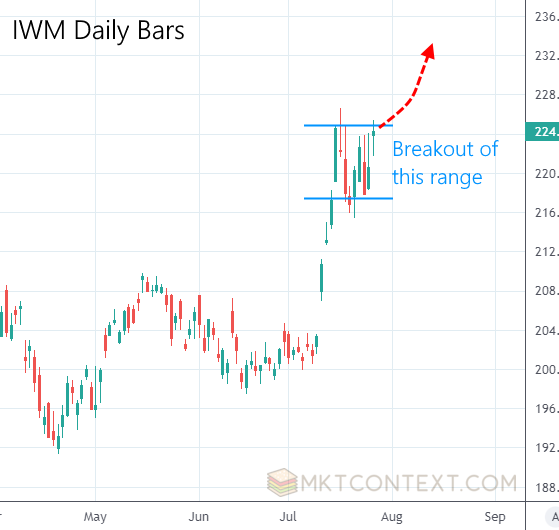
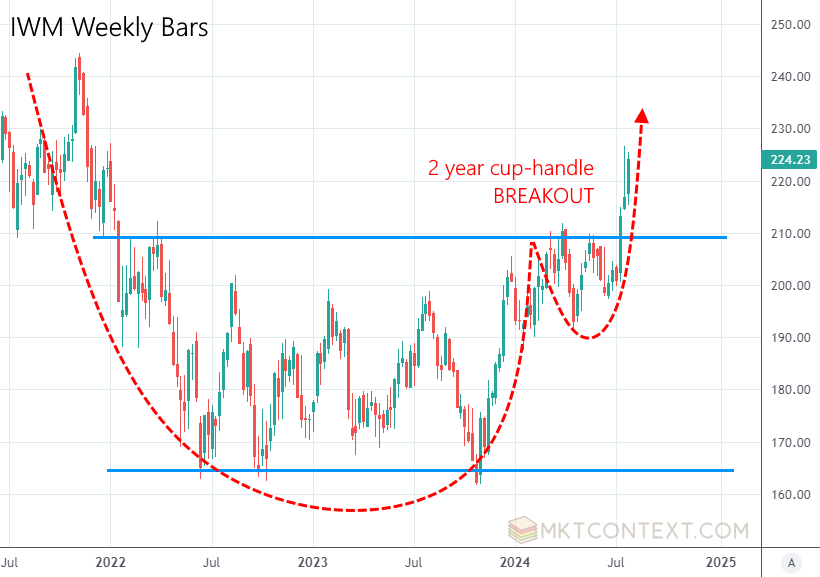
On the weekly chart we can see it is starting to break out of a two-year range and getting off the mat. These types of cup-and-handle breakout patterns signal a continuation rally is about to happen. Note that the rally in Nov 2023 saw the IWM rise 25% - an analog that we think can repeat again.
Longer term, we are about to see IWM reverse a decade-plus of underperformance relative to the SPX:

Last week we had a breadth thrust signal fire in the IWM. A breadth thrust occurs when the vast majority of stocks move up in tandem, and is a sign of changing market sentiment. It is a bit unusual to see it fire this late in the game, but nonetheless is a strong signal for outperformance over the next 12 months.
Our backtests show that when the IWM breaks out with the strength that it did (+10% in 10 days), forward returns over the next 12 months tend to be very good. This happens in about 75% of the instances that we studied. If we narrow it down further to instances outside of a recessionary period, the odds of success increase to 90%.
Positioning indicators (remember knowing the opponent’s poker hand?) in institutional funds and hedge funds are still relatively muted. They have obviously spiked due to the squeeze, but they are not at extremes yet. As the IWM continues to run, more investors will need to unwind their positions, adding support to small caps.
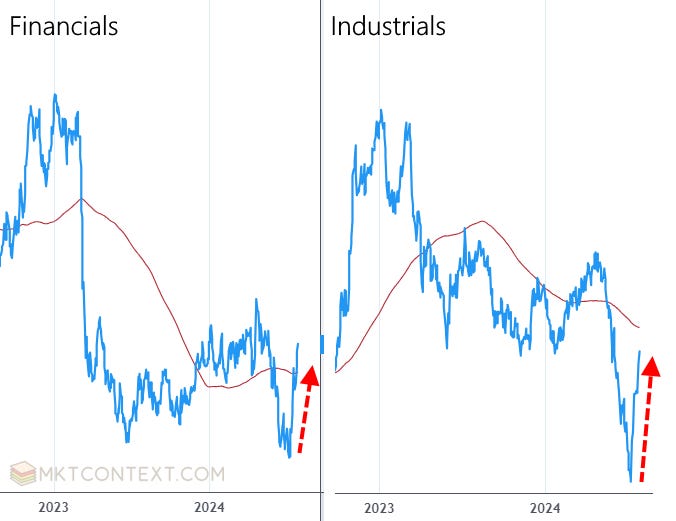
Looking under the hood at the sector composition, the Financial and Industrial sectors had been dropping like a rock because the market thought we were headed for a recession. These are traditionally cyclical sectors that react poorly to volatile economic data. But with Fed cuts in view and economic data inflecting, these two sectors have also recovered to their 200d moving average. This is a strong signal that the cyclical rally is underway!
Bottom line: we would be buyers of IWM on pullbacks or if the SPX gives us the all-clear signal.
That’s all for this week! We hope you enjoyed this deep dive on market timing, positioning analysis, and small caps. Subscribe now to receive regular updates on our trades:
Disclaimer: This publication is for educational purposes only. The authors are not investment advisors and nothing here is investment advice. Always do your own due diligence.
Like the way you write. Keep it up!
Great way to start and create engagement. Keep up good work! 💪🏻